
Schedule a Call Back
ICRA sees negative outlook on CE sales
2019-09-26
Pavethra Ponniah, Vice President & Sector Head ? Corporate Ratings, ICRA, said, ?Slow movement in award of road projects during the past several quarters, delays in payment to contractors, continued land acquisition issues and overall tightness in the financing environment has lead to a contraction in fresh equipment buying since early CY2019.?
During CY2018, the CE industry registered a growth of about 30 per cent in unit terms, driven by strong growth in all components, particularly backhoe loaders and excavators. This followed over two years of strong growth since CY2016-17. However, growth started contracting in early CY2019 in the run-up to the general elections. Till August CY2019, industry volumes have contracted by 16 per cent in the key product category of backhoe loaders, excavators and wheeled loaders, according to ICRA.
Roads has been the primary growth engine for CE demand in the past three years since CY2016. Road project awards contracted in FY2019. Following the formation of a stable government in May 2019, awards and demand for CE was expected to revive. Despite the increased capital outlay for roads, railways, and metro projects in the recent Union Budget, continued slowdown in project awards, payment delays to contractors, change in the awarding model for road projects and the overall uncertainty in the economy has led to a sharp decline in expenditure on roads during YTD FY2020.
Further, majority of the CE OEMs in India are joint ventures/subsidiaries of global majors. Import content in Indian CE is relatively high, with OEMs importing critical engine, hydraulic and track components, partly from the parent or the parent?s global supply chain. Volatility in the INR and the long lead time for inventory has added to the cost woes of the industry.
?The outlook on the sector could turn stable if demand environment improves on a consistent basis, with revival in public and private sector expenditure on infrastructure projects. Accommodative public policy and an improvement in buyer confidence would be critical for the same,? Ponniah added.
Subscribe Now
Subscribe to our Newsletter & Stay updated
RECENT POSTS
Popular Tags
Folliow us
Related Stories
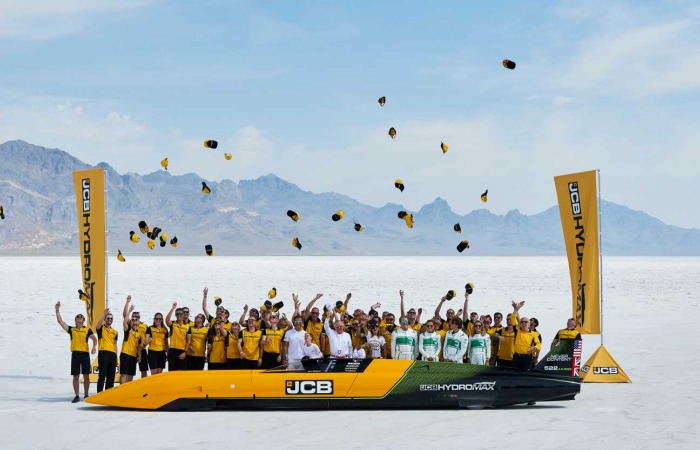
JCB Hydromax Sets Hydrogen Land Speed Record at 406.320 mph
British engineering major JCB has set a new world land speed record with its hydrogen-powered JCB Hydromax, achieving an average speed of 406.320...
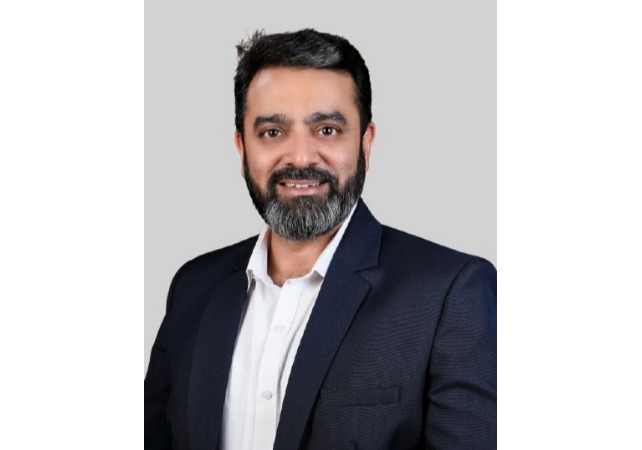
Schaeffler India Names Amit Bhalerao as Chief Operating Officer
Schaeffler India has appointed Amit Bhalerao as Chief Operating Officer (COO), effective August 10, 2026. He will lead the company's manufacturin...
BKT to Showcase Advanced Off-Highway Tyres at Bauma ConExpo
Balkrishna Industries Ltd (BKT) will showcase its latest off-highway tyre solutions at Bauma ConExpo India 2026, scheduled from September 15-18 a...